Reading Time: 14 Minutes
Difficulty Level: Beginner to Intermediate
Reviewed By: FinanceInfoIn Editorial Team
Table of Contents
-
The Sinking Feeling of Green Numbers
-
Quick Summary
-
Key Takeaways
-
The Difference Between the Dashboard and the Bank
-
Real-Life Math: How $10,000 in Profit Equals Bankruptcy
-
The Pressure to Instantly Upgrade Everything
-
Confusing Alternative: Real Growth vs Premature Splurging
-
When Suppliers and Vendors Change Their Rules
-
The YouTube Expert Perspective
-
The Hidden Cost of Customer Expectations
-
Honest Pros & Cons: The First Month of Black Ink
-
How to Survive the Success Trap Today
Quick Summary
Hitting your first month of profitability feels amazing, but it is actually the most dangerous phase for a new startup. Most founders confuse paper profit with available cash and accidentally spend money they do not have yet. Sudden expenses, delayed client payments, and the urge to scale too quickly completely drain the bank account. Surviving this phase requires slowing down, holding cash reserves, and ignoring the pressure to upgrade your operations instantly.
Key Takeaways
-
Profit on an accounting spreadsheet does not mean you have actual cash in your bank account to spend.
-
Scaling a business immediately after one good month often leads to a fatal cash flow crash.
-
Vendor terms, taxes, and software upgrades will secretly eat away your newly found profit margins.
-
Staying small and building a three-month cash buffer is the only safe way to handle initial success.
Mastering the Art of Holding Cash
When your bank account finally shows a positive balance, your brain naturally wants to celebrate. You've worked incredibly hard to get here. But the most successful founders do the exact opposite during this phase.
They lock down their spending completely. Instead of celebrating, they build financial defensive walls around their newly found money. They know a single profitable month is a lucky strike, not a permanent baseline.
To survive this tricky phase, you need a system that physically separates your available cash from your daily spending habits. If money is sitting in your main account, you will unconsciously find a reason to spend it. This is exactly why so many bootstrapped startups collapse right after their first taste of success — not from a lack of sales, but from a lack of cash discipline.
Pro Tip: Move thirty percent of your first major profit into a completely separate banking institution — not one connected to your everyday debit card, or you'll find a reason to spend it on sudden "emergencies."
You also need a strict waiting period for new purchases. If you think your business desperately needs a new computer or a bigger office, write the desire down and force yourself to wait ninety full days before buying it.
| Purchase Type | Immediate Action | 90-Day Evaluation Rule |
|---|---|---|
| New software tools | Stick to the free version | Only buy if the free version is losing you real clients |
| Hiring help | Do the extra work yourself | Only hire if you're physically unable to fulfill paid orders |
| Office upgrades | Stay at your kitchen table | Only upgrade if a client requires an in-person meeting |
If you still need the item after three months, and your profits have stayed steady, you can safely buy it. This kind of discipline is exactly what separates founders who bootstrap successfully from those who burn out chasing funding they never actually needed.
The Exact Step-by-Step Execution Guide
You can't just promise yourself you'll be careful with money — you need a physical action plan today. Here's exactly how to protect your new profits and prevent a sudden cash flow disaster.
Step 1: Open a Secondary "Vault" Account Walk into a completely different bank than the one you currently use, and open a basic business savings account with no debit card attached. This creates healthy friction — when you want to spend that money, you'll literally have to go to the bank to get it.
Step 2: Audit Your Net-30 Invoices Sit down with your accounting software and identify every client who owes you money. Calculate how many days it actually takes them to pay. If your average client takes 45 days, you now know you need 45 days of survival cash on hand at all times.
Step 3: Call Your Biggest Vendors Before placing your next big order, call your main suppliers and ask directly whether they offer extended payment terms for growing businesses. An extra two weeks to pay a supplier can be the difference between staying afloat and going under. The Small Business Administration has solid free guidance on negotiating terms like these.
Step 4: Set Up a Separate Tax Reserve Open one more sub-account (or a clearly labeled bucket at your vault bank) just for taxes — kept apart from your 30% profit reserve. From today onward, automatically move twenty percent of every incoming check into this tax-only account. Treat that money as if it already belongs to the tax office, not you.
Essential Financial Preparation Checklist
Before making any sudden moves with your new profits, gather this information and review it honestly:
- A printed list of all recurring monthly software subscriptions
- Your vendor agreements showing their strict payment deadlines
- A spreadsheet of unpaid client invoices and their exact due dates
- Your personal minimum living expenses (rent, groceries, basic bills)
- Any estimated tax documents required by your local government
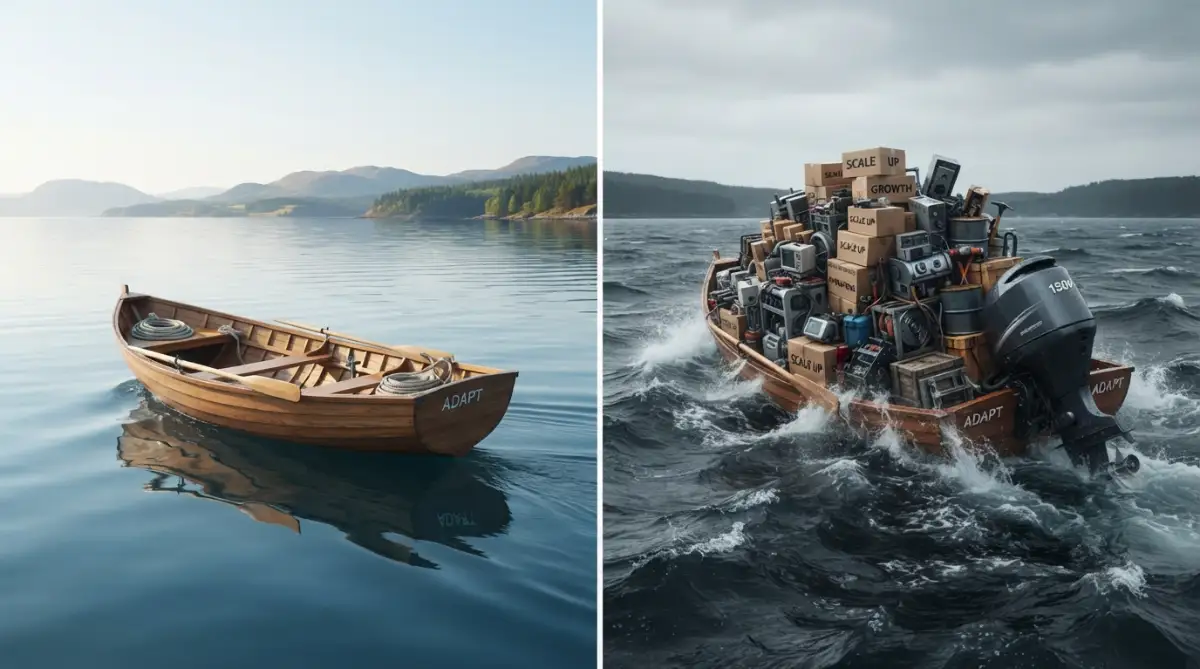
The Financial Traps That Destroy New Founders
Most money mistakes at this stage are driven by emotion, not math. You feel a sense of relief, so you let your guard down — trusting your gut instead of checking your spreadsheet.
One of the most common traps is treating new revenue like a personal ATM. You see ten thousand dollars in the account and decide it's safe to pay off your car loan — forgetting you owe eight thousand for next month's raw materials.
Another dangerous trap is the illusion of permanent demand. Just because you sold out in October doesn't mean November will look the same — markets shift, ads stop converting, and seasonal trends change fast. If you spend October's profit assuming November will be identical, one bad week can wipe you out. Build your safety net around your worst month, not your best one.
| Business Growth Myth | The Cold Hard Reality |
|---|---|
| Profit means you can finally relax | Profit means your operational risk has just doubled |
| You should reinvest every penny to grow faster | You need cash reserves, because unexpected bills are coming |
| Hiring people will reduce your daily stress | Hiring adds real payroll pressure every two weeks |
| Vendors will treat you better as you order more | Vendors often demand stricter terms for larger orders |
Many founders also overlook the unglamorous legal and administrative side of growth. When you're small, no one really notices you. Once real money starts moving through the business, you need proper insurance, cleaner books, and stricter compliance — and skipping these details can lead to painful fines. If you haven't formally registered your business yet, this is the moment to get it sorted, ideally without paying a fortune in legal fees.
Quick Action Checklist
Don't wait until tomorrow — take these actions right now, while the thought is fresh:
- Cancel at least two software tools you haven't used in the last 30 days
- Move 20% of every incoming payment into a dedicated tax reserve
- Send polite reminder emails to every client who's late on a payment
- Review your bills for the next 14 days and confirm you have cash to cover them
- Freeze all new hiring plans for the next three months
Negotiating Your Way Out of Trouble
If you hit a cash flow gap, communicate — hiding from your suppliers only makes things worse. If you know you can't pay a vendor by Friday, call them on Wednesday.
Tell them the truth: sales are great, but cash is currently tied up in client invoices. Offer a partial payment today and a firm date for the rest. Most vendors prefer honesty over silence.
| Negotiation Approach | Vendor Reaction | Likely Outcome |
|---|---|---|
| Ignoring their calls entirely | Anger, loss of trust | They cut off your supply line |
| Making a partial payment with an apology | Mild annoyance, but understanding | They keep shipping your materials |
| Calling three days before the deadline | Appreciation for the honesty | They offer an extra week to pay |
Building these relationships early is a real advantage — when your business hits a speed bump, your vendors act like partners instead of debt collectors.
Your Blueprint for Long-Term Survival
Making money in business is genuinely rewarding — proof that your work means something to the market. But you have to respect the money you make.
Don't let your ego push you into buying things you don't need. Keep your head down, respect your cash flow, and treat every dollar like it's your last. That's the same humble, careful mindset that helps founders build a business — and a financial foundation — that actually lasts.
I remember staring at my own bank screen during my first profitable month, fighting the urge to buy a new laptop to celebrate. Thank goodness I waited — two weeks later, my biggest client delayed a payment, and I needed every cent of that profit just to keep the lights on.
That moment taught me everything I needed to know about business survival: protect your cash first, and celebrate later. You've already done the hardest part by getting this far. Now you just have to stay in the game.
Which business expense are you planning to cut or delay this week? Let me know in the comments below!
Common Questions About Post-Profit Startup Survival
Why does a profitable business run out of money? Because profit is just an accounting term. It means you billed more than you spent — but if clients haven't paid their invoices yet, you have zero actual cash to pay your own bills.
How much cash should a new startup hold in reserve? Aim for three to six months of basic operating expenses in a separate savings account — enough to cover rent, minimal payroll, and software costs if sales suddenly drop to zero.
Should I hire employees after my first profitable month? Not right away. Wait at least three to six months to confirm the profit is consistent — hiring based on one lucky month can create a financial burden you can't sustain later.
What's the difference between paper profit and actual cash? Paper profit is the money you're legally owed under your sales contracts. Actual cash is what's physically sitting in your bank account, ready to use today.
How do I stop spending my business profits? Open a separate account at a different bank, with no debit card attached, and automatically move your profits there so impulse spending isn't an option.
Is it normal to feel stressed when making a profit? Yes — very normal. Real profit makes the business feel real, which naturally raises the pressure to perform and avoid costly mistakes.
When is the right time to upgrade my office or equipment? Only when your current setup is genuinely breaking down and costing you paying clients — not just because you want to look more established.
How can I get clients to pay their invoices faster? Require a deposit — say, fifty percent — upfront before starting work, and consider offering a small early-payment discount (like 2%) for invoices settled within five days.
Should I pay off personal debt with business profit? Pay yourself a modest, planned salary instead. Pulling large lump sums from the business to cover personal debt can leave the business short on cash exactly when it needs it.
What happens if I ignore my tax obligations after making a profit? Eventually, the government audits and hits you with penalties and interest — one of the most common causes of sudden bankruptcy for new founders.
-
Trusted Legal Resources
Disclaimer: The information in this article is for educational purposes only and does not constitute financial, legal, or tax advice. Every business situation is unique — consult a certified accountant or legal expert before making major financial decisions. FinanceInfoIn and its authors are not responsible for losses or liabilities arising from applying the concepts discussed here.
About the Author
Reviewed by Mithun Halder (Personal Finance & SEO Expert) & The FinanceInfoIn Editorial Team
The FinanceInfoIn Editorial Team researches personal finance, investing, insurance, mortgages, cryptocurrency, and consumer financial topics. Every article is carefully reviewed to provide clear, practical, and trustworthy educational information based on credible sources and industry best practices.
©2026 FinanceInfoIn. All rights reserved.