
Reading Time: 12 Minutes
Difficulty Level: Beginner to Intermediate
Reviewed By: FinanceInfoIn Editorial Team.
The Reality of Running Out of Money
Watching the remaining startup capital drop below four digits on a Tuesday morning is a heavy punch to the gut. I still remember sitting at my kitchen table, staring at a blank spreadsheet while my coffee went cold. My server costs were due in three days, and I had absolutely no idea how I was going to pay the freelance developer who built my core product.
This is the silent terror of the early-stage business world. You have a brilliant product, a passionate team, and maybe even a few early customers. Yet, the stress of not knowing if you can keep the lights on for another 90 days completely consumes your mind.
Every single decision feels like a gamble when you cannot see the financial road ahead. You hesitate to spend money on marketing because you are scared of running dry. At the same time, you worry that saving too much will completely stall your growth.
This lack of clarity ruins your sleep, destroys your weekend peace, and makes you second-guess your own leadership. Ordinary founders face this immense pressure daily, secretly wondering if everyone else has it all figured out. The truth is, most new business owners are flying completely blind.
They rely on basic bank balances instead of looking at future projections. But business survival requires looking at the road ahead, not just checking the gas gauge today.
Quick Summary
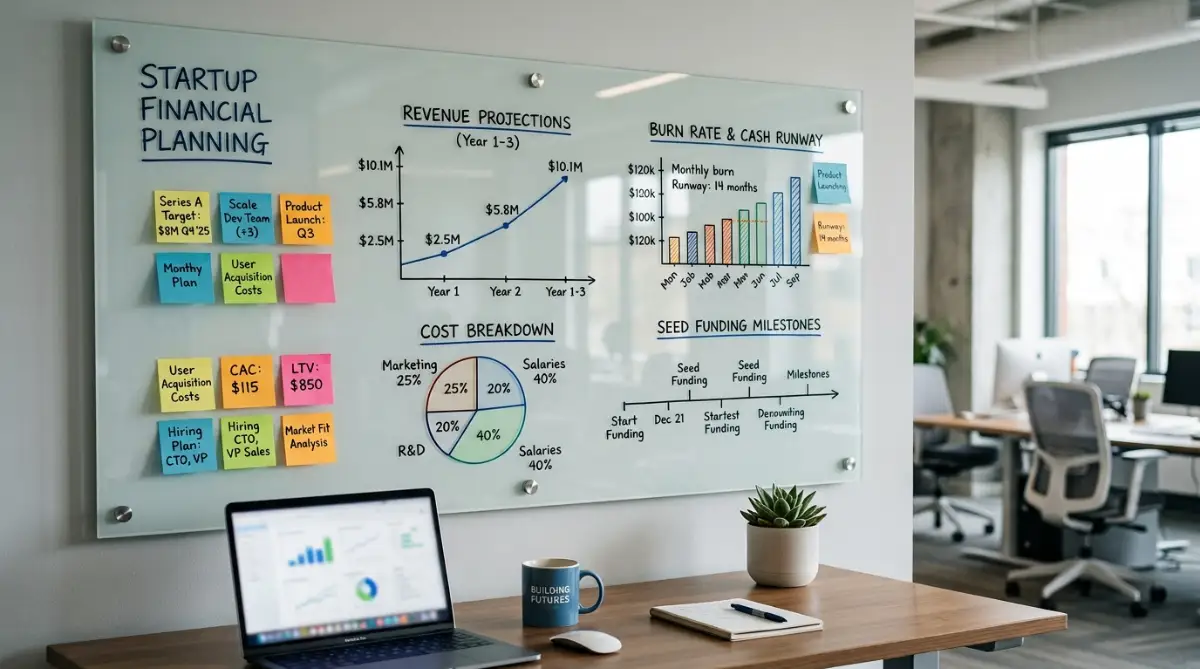
A startup's first financial forecast is a roadmap showing your future cash flow, expected expenses, and realistic revenue. It prevents sudden cash shortages by tracking exactly where your money goes. This guide breaks down how to build a simple, realistic financial model without needing an advanced accounting background.
Key Takeaways
- Never confuse your cash flow statement with your profit and loss statement.
- Always separate your fixed operational costs from your variable costs.
- Build your revenue projections from the bottom up based on actual customer behavior.
- Create three different financial scenarios: best case, worst case, and realistic case.
- Review and adjust your forecast at the end of every single month.
Why the First Financial Plan Always Feels Impossible
Most founders freeze when they hear words like "financial modeling" or "expense projections." The main reason is that you are trying to predict the future of something that barely exists yet. It feels like trying to map the ocean floor while swimming in a dark storm.
However, your early financial plan does not need to be a complex wall of numbers. It is simply a tool to help you understand your business runway. Your runway is exactly how many months you can survive before your bank account hits zero.
Think of this forecast as your business oxygen monitor. It tells you when you need to take a deep breath and when you need to find fresh air.
Confusing Alternative Comparison
People often mix up the core financial documents. Let's look at the biggest point of confusion for new founders.
The Cash Flow Reality Check: What You Actually Have
To start your forecast, you must face your current reality. You need to know exactly how much cash is sitting in your accounts right now. This is your starting line.
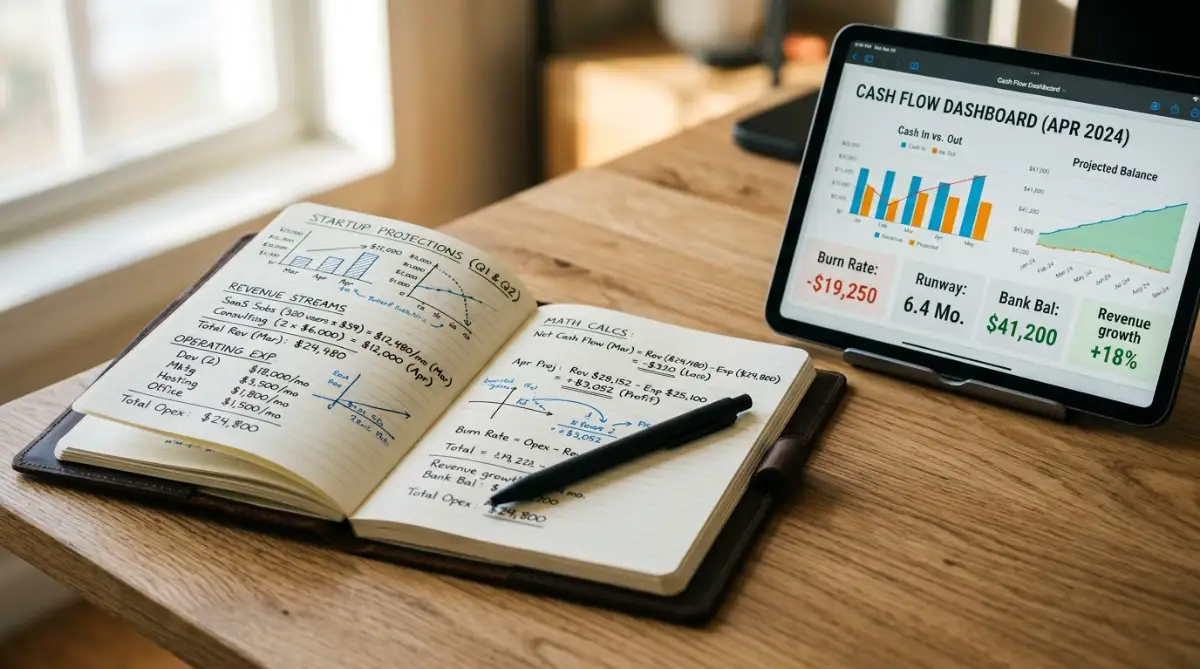
From here, you will map out your expected cash burn rate. Your burn rate is simply the amount of money your startup loses every month before making a profit. If you have ten thousand dollars in the bank and spend two thousand dollars a month, your runway is exactly five months.
Expert Tip: Always calculate your runway assuming you will make absolutely zero sales for the next three months. This forces you to see how long your safety net will actually hold.
Breaking Down Your Startup Costs
Before you can dream about millions in revenue, you must understand your expenses. Costs are the only part of your financial forecast that you can control with high accuracy.
Start by listing every single thing you pay for. Do not leave out the small things. A ten-dollar monthly software subscription might seem harmless, but ten of those add up to a significant drain on your limited capital.
Separate your expenses into two categories: fixed and variable.
Honest Pros & Cons Box: Doing Your Own Bookkeeping vs. Hiring Help
The Pros of DIY Bookkeeping:
- Saves a significant amount of money in the early days.
- Forces you to intimately understand every penny leaving your business.
- Helps you catch unnecessary software subscriptions immediately.
The Cons of DIY Bookkeeping:
- Takes time away from actually building your product or selling.
- Increases the risk of missing important tax deductions.
- Can lead to disorganized records if you fall behind for a month.
Building a Simple Revenue Model
Predicting revenue is where most founders make massive mistakes. They look at the total market size and assume they can capture one percent of it. This is called a top-down forecast, and it is incredibly dangerous for your survival.
Instead, you must build a bottom-up revenue model. A bottom-up model looks at your actual capacity to sell and your realistic customer acquisition numbers.
Real-Life Math Example
Let's look at Sarah, who is launching a software tool for local bakeries. Instead of saying "there are fifty thousand bakeries, I will get five hundred of them," Sarah does the real math.
Sarah can realistically make 20 cold calls a day. That is 100 calls a week, or 400 calls a month. From past tests, she knows 5% of her calls turn into meetings. That means 20 meetings a month. Out of those meetings, 20% actually buy her software.
This means Sarah will acquire exactly 4 new customers a month. If her software costs $100 a month, her projected new monthly revenue is $400. This math is grounded in reality, not fantasy. It helps her realize she needs to either increase her call volume or increase her software price to survive.
Pro Tip: I completely ruined my first six months of business by hoping customers would just find my website. My forecast assumed natural traffic growth without any marketing spend. Always tie your expected sales directly to a specific action or marketing cost you are actively managing.
Planning for the Unexpected Variables
A good financial forecast never assumes everything will go perfectly. Life happens. Equipment breaks. Ad campaigns fail. A major client delays their payment by two months.
If your financial plan only works when everything is perfect, your business is extremely fragile. You need a buffer.
Watch This Guide on Setting Up an Emergency Buffer
Understanding how to pad your startup budget can save you from total disaster during quiet months. Check out this quick breakdown on building a financial safety net for your small business.
This is why experienced founders use scenario planning. You should take your base numbers and create alternative realities.
How to Keep the Forecast Alive
A financial forecast is not a document you create once and hide in a folder. It is a living, breathing tool.
At the end of every month, you must sit down and compare your forecast to what actually happened. Did you spend more on ads than you planned? Did a customer pay late?
Update your spreadsheet with the real numbers. This practice, known as variance analysis, helps you get better at predicting the future. The first month, your guesses will be completely wrong. By month six, you will know exactly how your business breathes.
When you track your numbers this closely, the paralyzing anxiety starts to fade. You stop guessing and start leading. You might still have limited funds, but you will know exactly how far those funds will take you. This clear vision is the true foundation of a successful, long-lasting business.
Pushing Your Financial Strategy to the Next Level
Once you understand the basic mechanics of cash coming in and going out, you have to play offense. Managing a business means constantly finding smart ways to stretch every single dollar. This is where you move from simple survival to strategic growth.
One of the smartest moves you can make is delaying your outgoing cash while speeding up your incoming cash. You should always ask your suppliers for net-30 or net-60 payment terms. This simply means you have 30 to 60 days to pay your invoice after receiving the service or product.
On the flip side, make it incredibly easy for your customers to pay you instantly. Send invoices the exact minute the work is done. Offer slight discounts for clients who pay upfront for the entire year instead of month-to-month.
Pro Tip: I always set a calendar reminder every single Sunday evening to review my outstanding invoices. Chasing unpaid bills early prevents a sudden cash drought at the end of the month.
You also need to adopt a zero-based mindset. Every single month, treat your budget like it is starting from absolute zero. Do not just blindly pay a software subscription because you used it last month. Ask yourself if that tool is actively making you money right now.
When starting a business without outside funding, every subscription matters. A lean operation allows you to pivot quickly when the market changes. You never want to carry heavy financial baggage when you are trying to move fast.
Many founders assume that early-stage finance is all about aggressive expansion. However, experienced business owners know that defense wins the game. Keeping a tight grip on your numbers actually gives you the freedom to take calculated risks later.
Startup Finance: Myth vs. Reality
To keep a clear head, separate your personal emotions from the business bank account. A bad financial month does not mean you are a failure as a person. It just means a specific system in your business needs fixing.
Always look for free or low-cost ways to test your products before spending big money. Learning how to validate your ideas safely keeps your initial spending incredibly low. Let the market tell you what they want to buy before you build an expensive inventory.
The Silent Traps That Drain Startup Cash
Even the smartest entrepreneurs fall into financial traps. The most common error is being overly optimistic about how fast people will buy. We all want to believe our product will sell out on day one.
When you build a forecast entirely on blind optimism, you make terrible hiring and spending choices. If you hire three full-time employees expecting massive sales, and those sales delay by six months, you are stuck paying huge salaries with no income.
Another massive pitfall is forgetting about taxes and hidden fees. When you see ten thousand dollars in your business account, that is not all yours to keep. You must set aside a percentage for the government immediately.
If you ignore taxes, you will get hit with a massive, unexpected bill at the end of the year. This specific mistake is exactly why many promising new startups collapse so early. They spend the government's money, and then they cannot recover.
The Ripple Effect of Financial Mistakes
Founders also tend to throw money at problems instead of thinking through them. They buy expensive ad campaigns before fixing a broken website. Throwing cash at a broken system just burns your runway faster.
Before spending heavy amounts on marketing, make sure your core operations are legally and structurally sound. You can easily learn how to handle your basic legal setup cheaply without draining your early funds. Protect the foundation first, then build the house.
The Pre-Forecast Setup Checklist
Before you open a spreadsheet and start typing numbers, you need the right materials. Gathering these documents beforehand will save you hours of frustration.
Quick Action Checklist:
- Your last three months of personal or business bank statements.
- A complete list of every software, tool, and physical space you rent.
- Your current pricing sheet and estimated cost to produce one unit.
- Historical sales data (even if it is just a few early beta customers).
- Estimated tax rates for your specific state and business type.
- Your current credit card balances and any outstanding loan documents.
Having these exact numbers on your desk stops you from guessing. If you guess your expenses, your entire forecast becomes a work of fiction.
How to Build Your First Forecast Today
Taking action is the only way to conquer financial anxiety. You do not need a business degree to start organizing your money right now. Follow these direct steps to build your working model today.
Step 1: Map Your Baseline Survival Number
Open a blank document. Write down the absolute minimum amount of money your business needs to exist for one month. Do not include fancy marketing or new hires. Just rent, basic tools, and keeping the lights on.
Step 2: Project Your Realistic Income
Look at your current sales pipeline. How many deals are actually close to signing? Take that number and cut it in half to be safe. Write this conservative revenue number next to your survival cost.
Step 3: Define Your Runway Buffer
Check your current bank balance. Divide that total cash by your monthly survival number from Step 1. This gives you your exact runway in months. Now you know exactly how long you have to figure things out.
Step 4: Create a Weekly Check-In System
Pick one day of the week to be your "finance day." Spend just twenty minutes reviewing what you actually spent versus what you planned to spend. Adjust your forecast based on this real-world data.
The 90-Day Execution Timeline
By breaking the process down into steps, the math becomes manageable. You take back control of the steering wheel.
Taking Back Control of Your Business Future
Building a startup is one of the hardest things a person can do. It tests your patience, your energy, and your mental toughness. But running a business with a blindfold on makes the journey impossible.
A clear financial plan removes the heavy fog of uncertainty. It allows you to sleep peacefully, knowing exactly where your money is going tomorrow. You transition from reacting to every bill in panic to predicting your future with confidence.
I know exactly how scary it feels to face those numbers for the first time. My own early spreadsheets were a mess of red ink and terrifying runway calculations. But leaning into that fear and organizing my finances was the single turning point that saved my company.
You have the power to stop guessing and start building a secure foundation right now. Open that spreadsheet, face the reality of your numbers, and take the next step forward.
Which business expense category completely surprised you when you first started tracking it? Let me know in the comments below!
Smart Questions Founders Always Ask About Projections
Do I need expensive accounting software to start?
No, you absolutely do not need premium software on day one. A simple, well-organized spreadsheet is more than enough to track your early cash flow and expenses.
How often should I update my financial forecast?
In the beginning, you should review and update your numbers at the end of every single month. This frequent checking helps you spot bad spending habits before they ruin your runway.
Should I pay myself a salary from the start?
If your cash flow allows it, you should pay yourself a small, basic living wage to avoid personal burnout. However, many early founders delay their salary until the business hits consistent, recurring revenue.
What is the difference between revenue and profit?
Revenue is the total amount of money your customers pay you for your product or service. Profit is the money left over after you pay every single business expense and tax.
How do I forecast sales if I have no past data?
Start by researching industry averages for conversion rates and customer acquisition costs. Build a highly conservative model based on the actual number of sales calls or marketing emails you can realistically send each week.
Is it normal to lose money in the first year?
Yes, it is extremely common for startups to operate at a loss while they build their product and find their market. The key is making sure you have enough cash runway to survive this building phase.
How do I handle unexpected emergency expenses?
You should always build a buffer line item into your monthly budget specifically for unexpected costs. A good rule is to add a 10% to 15% padding on top of your expected operational expenses.
Can a financial forecast help me get a bank loan?
Yes, traditional lenders will immediately ask to see your cash flow projections and historical data. A clean, realistic forecast proves to the bank that you are a responsible business owner.
What should I do if my runway drops below three months?
You need to immediately freeze all non-essential spending and focus entirely on generating quick cash. This might mean offering steep discounts for upfront payments or taking on short-term freelance consulting.
Should I combine my personal and business bank accounts to save on fees?
Never combine your personal and business money under any circumstances. Mixing funds creates massive tax headaches and can destroy the legal liability protection of your company.