

🕒 Reading Time: 14 Mins | ✍️ Reviewed By: FinanceInfoIn Editorial Team
The Shock of an Unexpected Rate Hike
I opened my monthly loan statement on an ordinary Tuesday morning, expecting to see the exact same monthly charge I had been paying for months. Instead, my stomach instantly knotted. My required payment had silently jumped by over eighty-five dollars. A tiny, overlooked clause in my loan agreement had allowed my interest rate to adjust upward following a national economic shift.
That sudden, unexpected payment bump forced me to make painful cuts to my family's weekly budget just to keep the account in good standing. That stressful morning forced me to finally learn the hard truth: borrowing money without truly understanding the difference between fixed and variable rates is a dangerous gamble with your financial future.
Those unexpected payment bumps do not just drain your bank account; they drain your emotional energy. Millions of ordinary people wake up to this same silent stress every single month. You sign the paperwork thinking you have a solid handle on your budget, only to realize the rules of the game can change without your permission.
It feels incredibly unfair to work hard, budget your money carefully, and still fall behind simply because an invisible economic index shifted. The constant worry about whether your next payment will jump by fifty or a hundred dollars can ruin your sleep and spark bitter arguments with your partner.
On the flip side, paying a much higher premium just to lock in a guaranteed payment can leave you feeling like you are throwing hard-earned money out the window. You are caught in a frustrating trap between paying for peace of mind or gambling for a cheaper deal. Finding a way out of this trap requires stripping away the complex banking jargon and looking at the raw, honest facts of how these financial products actually operate.
Quick Summary
Deciding how to borrow money often comes down to predicting the unpredictable. A fixed option guarantees that your interest and monthly payments will never change, offering ultimate peace of mind. A variable option usually starts cheaper but can adjust higher or lower based on the broader economy. Your final decision should depend on your current cash flow, how fast you plan to pay off the debt, and your personal tolerance for financial risk.
Key Takeaways
- Guarantees protect your budget against unexpected market spikes.
- Floating rates often save you money initially but carry hidden long-term risks.
- Short-term borrowing usually favors adjustable options, while long-term debt demands stability.
- Always calculate the worst-case scenario before signing any financial agreement.
- Early payoff penalties can secretly destroy the savings of a cheaper initial deal.
The Foundation of Borrowing Money
Before we can figure out which path is right for your wallet, we need to completely understand what these two terms mean in the real world. Banks love to use complicated words, but the basic concepts are actually very simple.
Think of a fixed interest option as buying a plane ticket. You pay a specific price, and no matter how expensive the fuel gets during the flight, your ticket price never goes up. You know exactly what you owe from day one until the balance hits zero.
A variable or adjustable option is more like paying for an Uber during a busy weekend. The price might start out incredibly cheap when demand is low. However, if it starts raining or a concert lets out, that surge pricing hits, and suddenly your ride becomes terribly expensive.
Breaking Down the Math: David vs. Sarah
To truly see how this works, let us look at a real-life math example involving two imaginary friends, David and Sarah. Both of them need to borrow $10,000 to renovate their kitchens, and they both want to pay it back over five years.
Sarah hates surprises. She chooses a guaranteed fixed rate of 6%. Her math is perfectly clear. She will pay exactly $193 every single month for 60 months. By the time her kitchen is paid off, she will have paid $1,580 in total interest. She sets up an automatic transfer and never has to look at the loan again.
David wants the cheapest deal possible today. He chooses a variable option that starts at a very attractive 4%. For the first year, his payment is only $184. He feels great about saving nine dollars a month compared to Sarah.
However, in year two, the central banking index rises. David’s rate suddenly jumps to 7%, pushing his payment to $197. By year four, the economy shifts again, and his rate spikes to 9%. His payment is now $205. In the end, David actually pays $1,750 in total interest. He took the risk to save money, but market fluctuations ultimately cost him more.
The Heavy Cost of Financial Surprises
Sometimes the best way to understand the true impact of interest rate changes is to hear it from financial professionals who watch people make these mistakes daily. Watch this quick breakdown to see exactly how banks calculate your monthly obligations before we dive into the hidden traps of alternative borrowing.
Understanding the math is only half the battle. You also have to understand how your brain reacts to financial stress. Predictable monthly payments allow you to sleep soundly at night.
If your income is highly predictable, like a salary that never changes, sudden payment increases can instantly destroy your monthly budget. You cannot easily pull extra cash out of thin air just because the bank demands it.
On the other hand, if you get large yearly bonuses or earn heavy commissions, you might have the cash flow to handle a variable bump. You might even plan to throw your entire bonus at the principal balance to wipe it out before the rate has a chance to rise.
Pro Tip: I once took out an adjustable auto loan just to secure a monthly payment that was fifteen dollars cheaper. I completely ignored the fine print. Two years later, the rate adjusted so high that my loan balance was barely moving downward, and I ended up trading the car in at a massive loss just to escape the debt. Always read the maximum cap limit on any adjustable agreement.
Clearing Up the Biggest Confusion
People constantly mix up installment borrowing with revolving credit. This is a massive mistake that can severely damage your credit score if you do not understand the mechanics.
When you take out a traditional personal loan, you get a lump sum of cash on day one. You then pay it back in structured, scheduled pieces.
Credit cards operate in a completely different universe. They are almost always variable, but they also allow you to carry a balance indefinitely as long as you meet a tiny minimum requirement. Let us clear up the confusion directly.
When you use a credit card for a massive purchase and only pay the minimum, the variable interest compounds aggressively. A traditional loan forces discipline upon you, while a credit card encourages you to stay in debt forever.
The Honest Pros and Cons Box
To make this decision as easy as possible, you need to weigh the good against the bad without any marketing fluff. Here is the absolute truth about both options.
The Fixed Option:
- Pros: Complete predictability for your family budget. Protection against wild economic inflation. Zero stress about monitoring national interest indexes.
- Cons: You usually pay a premium upfront for this safety. If the national economy crashes and rates drop, you are stuck paying your higher original amount.
The Variable Option:
- Pros: Offers a much cheaper starting payment. Excellent for aggressive debt payers who plan to clear the balance in just a few months. If national rates drop, your payment gets cheaper automatically.
- Cons: High risk of payment shock. Budgeting becomes a moving target. The mental stress of watching economic news can be exhausting.
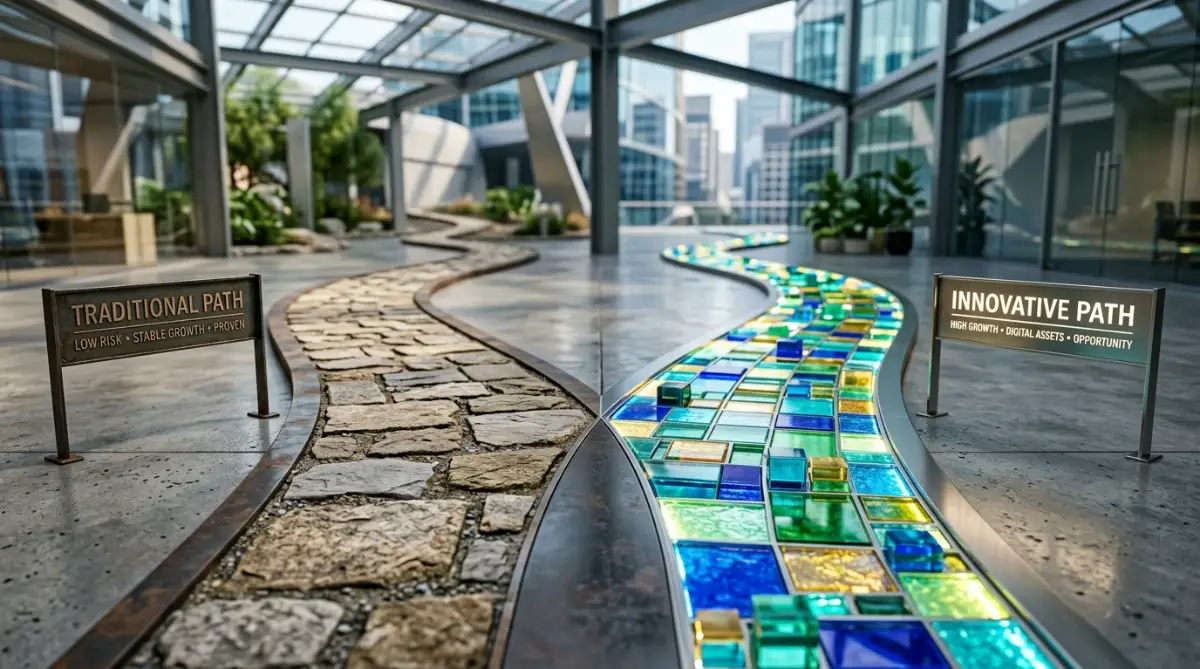
Matching the Debt to Your Life Strategy
How long do you plan to hold onto this money? This single question should drive your entire decision-making process. The longer you hold debt, the more time the market has to behave unpredictably.
If you are borrowing money to buy a house that you plan to live in for thirty years, a variable option is incredibly dangerous. Over three decades, the economy will undoubtedly go through multiple recessions and booms. A fixed option acts as a solid anchor against those wild storms.
Expert Tip: Pay close attention to the margin rate on an adjustable agreement. The bank will often advertise a low index rate, but they hide a fixed margin percentage on top of it. Always ask the lender to calculate the maximum possible payment you could face if the rate hits its legal ceiling.
Conversely, if you are flipping a house and only need the money for six months, a variable option might be brilliant. You get the lowest possible starting cost, and you will sell the property long before the bank has a chance to adjust your payment upward.
Looking Beyond the Monthly Payment
Many people get so obsessed with the monthly payment amount that they completely ignore the amortization schedule. This is the timeline that shows exactly how much of your money goes toward interest versus the actual principal balance.
With fixed agreements, this schedule is permanently printed on day one. You can run your finger down the paper and see exactly what you will owe on a random Tuesday three years from now.
Adjustable agreements have an amortization schedule that is basically written in pencil. Every time the index changes, the bank recalculates how much of your payment goes toward the principal. If rates spike highly enough, you might find that you are making full payments but your actual debt balance is barely shrinking at all.
Knowing When to Walk Away
Never let a pushy loan officer rush you into signing a variable agreement just because the initial numbers look pretty on a computer screen. They get paid to close deals, but you are the one who has to live with the financial consequences for years.
If you do not completely understand how the cap limits work, walk away. If you cannot afford the maximum possible payment on an adjustable term, do not sign the paper. It is always better to delay a purchase than to trap yourself in a financial agreement that slowly drains your bank account.
Choosing the right borrowing path is not about being a math genius. It is about being honest with yourself regarding your spending habits, your job security, and your ability to handle stress. Protect your peace of mind first, and protect your wallet second. When you prioritize stability over a temporary discount, you put yourself in a position to actually build long-term wealth instead of just surviving from one payment to the next.
Strategies to Outsmart the Banking System
Understanding the basic differences between borrowing options is a great start. Now, we need to look at how smart borrowers actively manage these debts to keep more money in their own pockets. You do not just sign a paper and forget about it.
One of the most powerful moves you can make is creating a fake fixed payment for your variable debt. If your adjustable payment starts at $300, but the fixed option would have been $400, do not just spend that extra $100. Instead, send that extra hundred dollars directly toward your principal balance every single month.
This simple strategy acts as a personal insurance policy against future market changes. If the national indexes eventually rise and your required payment jumps to $375, you will not feel any financial shock because your brain and your budget are already used to paying $400. Even better, those early extra payments reduce your core balance rapidly, meaning the bank has less money to charge interest on when rates do go up.
Pro Tip: Always ask your lender if your adjustable agreement includes a conversion clause. Many banks will allow you to switch a variable product into a permanently fixed one later on for a small fee, giving you the perfect escape route if the economy gets unstable.
If you are already feeling squeezed by your current monthly obligations, learning how to create a personal budget when living paycheck to paycheck is your very first line of defense. A solid budget reveals exactly how much flexibility you truly have before you take on a new financial commitment.
Sometimes, borrowing money is less about the interest cost and more about strategic timing. Economic experts often publish transparent data on where lending costs might head next. You can actually check trusted national resources like the Federal Reserve economic data reports to see current market trends before you make a massive financial commitment.
The Most Dangerous Borrowing Traps
People often walk into banks feeling confident, only to make tiny errors in judgment that cost them thousands of dollars down the road. The most devastating mistake is falling in love with the introductory teaser rate. Banks aggressively advertise incredibly cheap starting payments to get you through the door.
You might see an advertisement for a 2% adjustable rate and assume that is your permanent cost. The trap snaps shut a few months later when the introductory period ends and the rate instantly resets to 8%. Suddenly, you are trapped in a payment you cannot afford. This is why understanding why your credit card application was denied and how to fix it today is so tied to your overall debt health. Lenders look closely at how you manage these shifts.
Another massive pitfall is completely ignoring prepayment penalties. Imagine you choose an expensive guaranteed rate because you want safety. A year later, you get a new job, make more money, and want to pay the whole balance off early to save on interest. You call the bank, only to discover a hidden clause that charges you a massive penalty just for paying them back faster.
Many borrowers also fail to understand the math behind the "index plus margin." With adjustable agreements, the bank uses a public economic number (the index) and adds their own guaranteed profit percentage (the margin) on top of it. If the index is 3% and their margin is 4%, your actual cost is 7%. People only look at the small index number and get completely blindsided by the margin.
Taking Control: Step-by-Step Execution Guide
Reading about these financial mechanics is helpful, but you actually need to apply this knowledge when you sit across the desk from a loan officer. Do not let them rush your decision. You are the one paying the bill, so you set the pace of the conversation.
Step 1: Demand the Worst-Case Scenario Document
Before signing anything, ask the lender to print out a clear schedule showing the absolute highest payment possible under an adjustable agreement. If looking at that maximum number makes your stomach drop, immediately switch your request to a fixed agreement.
Step 2: Optimize Your Borrowing Profile
Banks reserve their safest and cheapest options for people with excellent financial habits. Before you apply for a large amount of money, take time to learn how to lower your debt to income ratio before a mortgage application. Paying down small, annoying debts first makes you look much less risky to the underwriter.
Step 3: Secure Your Safety Net
Never take on a fluctuating financial obligation without having cash reserves. If you choose an adjustable path to save money today, make sure you know how to build an emergency fund when your income is small. That cash buffer is the only thing that will save you if your payment suddenly jumps before you get your next raise at work.
Step 4: Review the Official Loan Estimate
The government requires lenders to provide a standardized form called a Loan Estimate. Read page two extremely carefully. This specific page outlines exactly how much your rate can increase at the first adjustment, and the maximum it can reach over your lifetime.
Quick Action Checklist
To make this process as smooth as possible, gather these exact items before you even contact a lender. Having your paperwork organized shows the bank you are a serious and responsible borrower.
- Proof of Stable Income: Collect your last 30 days of pay stubs and your last two years of tax returns to prove you can handle the monthly obligations.
- Your Complete Debt List: Write down every single minimum payment you currently make. You can learn how to calculate your debt to income ratio for a home loan to see exactly what the bank sees.
- Asset Verification: Print out your most recent checking, savings, and investment account statements.
- The Target Budget: Write down the absolute maximum monthly payment you can afford without losing sleep at night.
- Identification Documents: Have a valid government ID and proof of your current physical address ready to go.
Your Blueprint for Financial Peace
Making smart choices about borrowing money does not require a degree in economics. It simply requires you to be completely honest with yourself about your comfort level with the unknown. If you value a quiet mind and a perfectly organized budget above all else, lock in your terms and never look back.
If you are highly disciplined, aggressively paying down principal, and planning to clear the obligation quickly, taking a calculated risk on a fluctuating agreement can speed up your wealth-building journey.
I know how incredibly heavy the weight of financial decisions can feel. My own journey to financial stability only started when I stopped guessing and started demanding clear answers from my bank. You have the power to protect your hard-earned money, and it starts with asking the right questions today.
Common Questions About Navigating Loan Options
What happens to my variable payment if the economy crashes?
If national interest rates drop significantly, your adjustable payment will generally decrease. This is one of the few times a fluctuating agreement works heavily in your favor, as your monthly obligations naturally become cheaper.
Can I change a fixed agreement to a variable one later?
You cannot simply swap the terms on your current contract. You would have to completely refinance the debt by taking out a brand new adjustable agreement to pay off the old guaranteed one.
Is a credit card considered a fixed or va