

Reading Time: 15 Minutes
Difficulty Level: Beginner to Intermediate
Reviewed By: FinanceInfoIn Editorial Team
The Sickening Feeling of a Roadside Emergency
My hands were literally shaking as I stood on the shoulder of Route 66. Steam was hissing from my crushed hood, and the driver I just rear-ended was already pacing back and forth, yelling into his phone.
At that exact second, I was not thinking about my own safety. My brain was completely consumed by sheer financial panic. I had exactly twelve dollars in my checking account until payday.
How on earth was I going to pay for his ruined bumper, let alone my own wrecked car? I knew I had an auto policy because the law required it, but I had zero idea what it actually covered.
I paid a random bill every month, stuffed a paper card in my glovebox, and hoped I never had to use it. That lack of knowledge almost cost me my entire financial future.
Millions of people drive to work every single day with this exact same blind spot. They pay hard-earned money to major companies without understanding the product they are actually buying.
When you do not know how your coverage functions, an ordinary Tuesday afternoon fender bender can instantly ruin your savings. The stress of not knowing if you are protected creates a heavy, invisible weight on your shoulders every time you get behind the wheel.
It is time to fix that today. Let us break down exactly what you are paying for, so you never have to panic on the side of a highway like I did.
Quick Summary
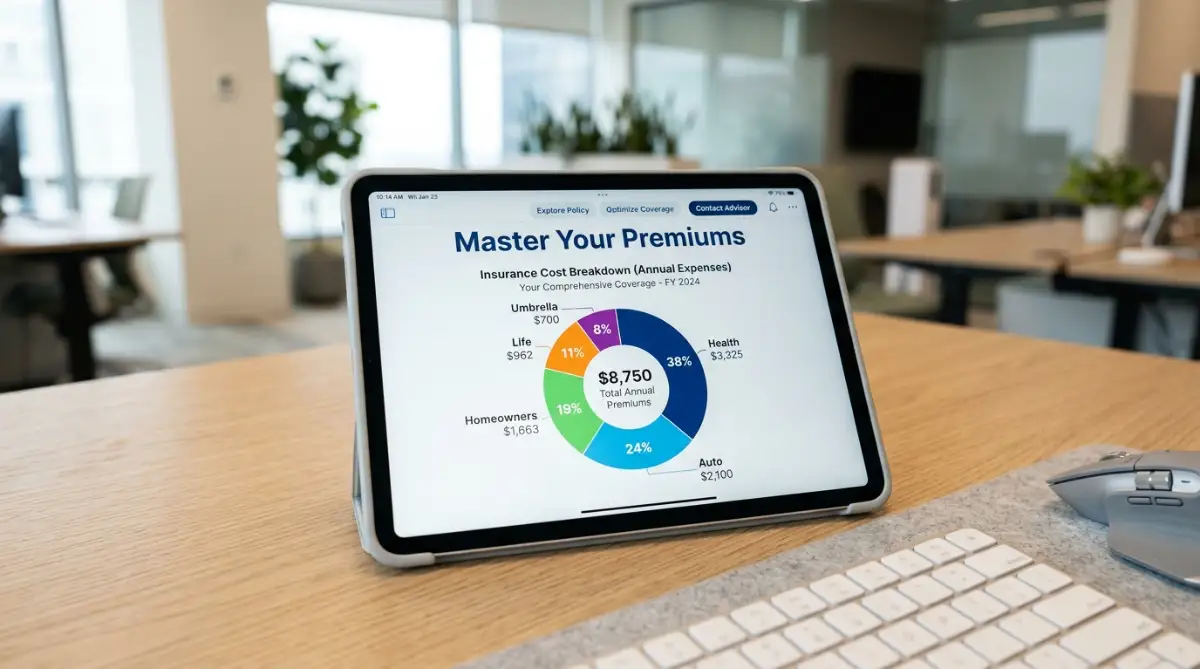
Car insurance is a financial safety net where you pay a small monthly fee to transfer the massive financial risk of an accident to a massive company. Your policy is broken down into specific types of protection, primarily liability, collision, and comprehensive. By understanding your deductible and premium, you can easily customize a plan that fits your budget. Knowing these simple rules prevents financial disaster when the unexpected happens.
Key Takeaways
- Liability is mandatory: It pays for the damage you cause to others, not your own vehicle.
- Your deductible matters: Choosing a higher deductible will lower your monthly bill.
- Full coverage is a myth: You must specifically add collision and comprehensive to protect your own car.
- Rates are personal: Your driving record, location, and even credit score change how much you pay.
Translating the Alphabet Soup of Auto Policies
People often get highly confused by the legal jargon used in their paperwork. The industry loves to use complicated words for very simple concepts.
Think of your policy like a customizable pizza. The crust is the mandatory coverage required by law, and the toppings are the extra protections you choose to add.
The biggest mistake beginners make is assuming that having "insurance" means everything is automatically paid for. That is completely false.
If you do not buy the right specific "topping," the company will not pay a single dime for that specific type of damage. Let us clear up the most common point of confusion right now.
As you can see, simply buying the cheapest legal option leaves your own wallet completely exposed.
Real-Life Math: Sarah's Parking Lot Nightmare
Let us look at a real-world example to make this perfectly clear. Sarah was backing out of a tight spot at the grocery store and accidentally scraped her door against a concrete pillar.
The repair shop gave her a shocking estimate of $2,500 to fix the deep scratches and massive dent. Thankfully, Sarah had Collision coverage with a $500 deductible.
This means Sarah simply pays her $500 portion out of her own pocket first. Once she pays that, the insurance company steps in and covers the remaining $2,000.
Instead of draining her emergency savings, she handled a massive problem for a fraction of the total cost. This is the exact math behind how financial risk transfer works.
The Core Elements of Financial Protection Explained
To truly understand this system, you need to master two very basic vocabulary words. These two words completely control how much money leaves your bank account.
The first word is your Premium. This is the exact amount of money you pay the company every month, or every six months, just to keep your policy active.
Think of the premium like a subscription fee. You pay it whether you drive 100 miles a day or leave your car parked in the garage all week.
The second word is your Deductible. This is your personal skin in the game. It is the amount you agree to pay upfront before the company opens their checkbook to help you.
If you think of this like going to an exclusive club, your premium is the monthly membership fee. Your deductible is the cover charge you pay at the door on the night you actually decide to visit.
There is a direct, undeniable relationship between these two numbers. If you want a cheaper monthly bill, you must accept a higher deductible.
If you want to pay almost nothing out of pocket after a crash, you must pay a much higher monthly premium. It is a simple balancing act based on your current savings.
Honest Pros & Cons: Choosing Your Deductible
The High Deductible (e.g., $1,000)
- Pros: Your monthly premium drops significantly, saving you cash right now.
- Pros: Great if you are a very safe driver who rarely gets into accidents.
- Cons: If you crash, you must suddenly find $1,000 in cash before your car gets fixed.
- Cons: Minor scrapes and scratches might not be worth repairing at all.
The Low Deductible (e.g., $250)
- Pros: Zero panic after a crash, because $250 is easy to pull from savings.
- Pros: Makes it highly affordable to fix minor cosmetic damage quickly.
- Cons: Your monthly premium will be aggressively high.
- Cons: You might pay more in monthly fees over five years than the deductible would have cost.
Expert Tip: Never choose a deductible that is higher than the amount of money you currently have sitting in your emergency savings account. If you pick a $1,000 deductible but only have $300 in the bank, you will not be able to get your car out of the repair shop.
How the Claims Process Actually Functions
So, you have paid your premium, and the worst has happened. You are standing on the road with a broken vehicle. What happens next?
The process of asking the company for help is called filing a claim. It is not as scary as people make it out to be.
First, you always ensure everyone is physically safe and call the police to get an official accident report. This piece of paper is incredibly valuable because it officially documents what happened.
Next, you will open your provider's mobile app or call their 1-800 number. You will tell them exactly what happened, where it happened, and who was involved.
Watch this quick visual breakdown to see exactly what happens behind the scenes after you hang up the phone with your agent.
After you report the incident, the company assigns a claims adjuster to your case. This person is essentially a financial detective.
Their entire job is to review the police report, look at the photos of the damage, and calculate exactly how much money the repairs will cost.
If your vehicle is totally destroyed, they will research the current market value of your exact car. They will then cut you a check for that amount, minus your deductible.
The "Fault" Factor and How It Impacts Your Wallet
The adjuster is also trying to determine who is officially at fault for the crash. This is a massive deal for your future finances.
If the other driver is 100% at fault, their liability coverage pays for everything. You will not have to pay your deductible, and your future rates generally will not go up.
However, if you are at fault, your collision coverage kicks in to fix your car. You will pay your deductible, and the company will pay the rest.
The downside is that because you caused the crash, the company now views you as a higher risk. When your policy renews, you can expect your monthly premium to increase.
Smart Tricks to Lower Your Monthly Bill
You are not stuck paying whatever random number the algorithm spits out at you. There are highly effective ways to force that number down.
Companies calculate your rate based on risk. If you can prove to them that you are extremely unlikely to file a claim, they will happily charge you less money.
They look at your driving history, your age, where you park your car at night, and surprisingly, your credit score. People with good credit mathematically get into fewer accidents.
I used to think my rate was permanent. Pro Tip: I realized I was throwing money away when I actually called my agent and just asked, "What discounts am I currently missing out on?" I instantly saved $25 a month because I worked from home and was driving less than 5,000 miles a year. You have to ask for the savings; they will not just hand them to you.
You should actively shop around for a new rate every single year. Loyalty to a massive corporation does not pay off in this industry.
Different companies use different math formulas to calculate risk. One company might hate that you live in a specific zip code, while another company does not care at all.
By spending just twenty minutes getting fresh quotes online, you can often find identical coverage for hundreds of dollars less per year.
Understanding this system is no longer a mystery. You now know exactly what liability means, how deductibles work, and why your premium changes.
You hold the power to protect your finances. Take a few minutes this weekend to pull out your current paperwork and make sure your safety net is actually strong enough to catch you.
Smart Strategies to Master Your Auto Protection
Now that you understand the basic mechanics of how these companies operate, it is time to level up your strategy. You do not have to accept the first price quote they hand you.
Many people treat their auto policy like a slow leak in a tire. They know money is slowly dripping away, but they ignore it because fixing it seems like too much work.
In reality, optimizing your coverage takes less than an hour. The easiest way to start is by understanding your insurance declaration page, which is simply the summary sheet showing exactly what you pay for.
Once you know your current baseline, you can start cutting the fat. For example, if you drive an older car that is barely worth $3,000, paying for expensive collision coverage mathematically does not make sense.
If that older car gets totaled, the company will only write you a check for its actual cash value. You might be paying $500 a year in premiums just to potentially get a $2,000 payout.
Pro Tip: I highly recommend dropping collision and comprehensive coverage once your yearly premium equals 10% or more of your car’s total market value. Take that money and put it into a high-yield savings account instead.
You should also look into usage-based driving programs if you work from home. By letting the company track your miles through a simple smartphone app, you can aggressively slash your monthly bill.
This directly ties into lowering your auto insurance premium by proving you are a low-risk driver. Less time on the road means less chance of an accident.
Common Mistakes
Even smart drivers make expensive errors when setting up their financial safety nets. The most dangerous mistake is choosing the absolute state minimum liability limits just to save a few dollars a month.
If you cause a multi-car pileup, state minimums will not come close to covering the medical bills or vehicle repairs. Once your policy hits its maximum payout, the other drivers will legally sue you for the rest of the money.
They can come after your house, your savings, and even garnish your future paychecks. Saving twenty dollars a month is never worth risking your entire life savings.
Another massive pitfall is assuming your policy covers absolutely everything. Many people are shocked to learn why auto claims get denied after a disaster strikes.
For instance, if your laptop is stolen out of your backseat, your auto policy will not pay for it. That actually falls under your renters or homeowners coverage.
People also completely misunderstand what comprehensive protection actually covers. They think it means "everything," but it only applies to non-driving disasters like a tree falling on your hood or a deer jumping in front of your headlights.
Myth vs Reality
Your Step-by-Step Execution Guide
Knowledge is useless if you do not actively apply it to your wallet. You need to treat your coverage like a yearly financial checkup.
To make this completely stress-free, I have broken down the exact steps you need to take this week. Do not put this off, because an accident can happen on your very next drive.
Step 1: Locate Your Declaration Page
Log into your current provider's mobile app or website. Download the PDF document that lists your specific coverages, deductibles, and limits.
Step 2: Evaluate Your Current Car's Worth
Go to a free valuation site like Kelley Blue Book or Edmunds. Find out exactly how much cash your car would sell for if you put it on the market today.
Step 3: Analyze Your Emergency Fund
Look at your savings account. If you only have $500 saved up, you must lower your deductible to $500, even if it slightly raises your monthly bill.
Step 4: Shop the Competition
Use a free online comparison tool to get three different quotes from competing companies. Make sure you are comparing the exact same coverage limits so the math is accurate.
To help you stay organized, here is your practical list to get started today.
Quick Action Checklist
- Locate your current declaration page on your phone or in your glovebox.
- Write down your current monthly premium and your collision deductible.
- Check your car's current market value online.
- Verify if you have uninsured motorist protection active.
- Call your current agent and specifically ask for unapplied discounts.
- Get at least two fresh quotes from competing providers.
Understanding exactly what your policy covers and excludes before you need to file a claim is the ultimate financial superpower. It puts you in the driver's seat of your own financial destiny.
Securing Your Peace of Mind on the Road
At the end of the day, paying for a policy is not just about following the law. It is about buying yourself total peace of mind every time you turn the ignition key.
You work incredibly hard for your money, and one random patch of ice on the highway should not wipe out your bank account. By taking control of your deductibles and understanding your limits, you build an unbreakable financial shield around your family.
I know exactly how stressful this topic can feel, but taking just thirty minutes to audit your coverage will make you feel instantly lighter. You have the knowledge now, so take the wheel and protect your hard-earned assets.
Which part of your policy are you planning to double-check today? Let me know in the comments below!
Common Questions About Auto Policies
1. Does my policy cover rental cars when I go on vacation?
In most cases, your active personal coverage extends to a rental car for normal use. However, you should always double-check with your agent before declining the rental counter's expensive daily protection.
2. Will my monthly rate go up if someone else hits me?
If you are completely free of fault, your rates generally remain exactly the same. The at-fault driver's provider carries the financial burden of paying for the damages.
3. Do I actually need gap coverage?
If you owe the bank more money than your car is currently worth, gap coverage is highly recommended. It pays the difference if your car is totaled, so you do not have to keep making loan payments on a destroyed vehicle.
4. What happens if I let my friend drive my car?
Coverage usually follows the vehicle, not the specific driver. If your friend crashes your car, your policy will likely have to pay for the damages, and you will have to pay the deductible.
5. Does my credit score really change how much I pay?
Yes, in most states, companies use a credit-based insurance score to predict your risk. Maintaining a healthy credit history helps prove you are financially responsible, which lowers your rates. (Note: States like California, Hawaii, and Massachusetts have legally banned insurers from using credit scores to determine auto insurance rates).
6. What exactly is uninsured motorist protection?
This is a critical safety net that pays your medical bills and repairs if you are hit by someone who illegally has no coverage. It protects you from having to pay out of pocket for their terrible mistake.
7. Is my stolen laptop covered if it was in the trunk?
No, auto policies only cover the physical vehicle and its permanently attached parts. Stolen personal belongings are usually claimed under your active renters or homeowners policy.
8. How long does a speeding ticket impact my monthly bill?
Minor traffic violations generally stay on your driving record and impact your rates for about three to five years. Driving safely moving forward is the best way to let those penalties naturally expire.
9. Should I always file a claim for minor scratches?
Filing a claim for minor damage that costs less than your deductible is mathematically useless. Even if it costs slightly more than your deductible, paying cash might be smarter to avoid a future rate increase.
10. Can I cancel my policy at any time if I find a better deal?
Yes, you are never permanently locked into a contract. If you find a much better rate, you can switch companies today, and your old provider will refund you for the unused days.