
Reading Time: 12 Minutes
Difficulty Level: Beginner to Intermediate
Reviewed By: FinanceInfoIn Editorial Team
The Silent Rejection: A Number You Didn't Know Mattered
Sitting in that small, overly air-conditioned bank branch, my palms were sweating. I had printed out all my pay stubs, organized my tax returns, and even wore a collared shirt.
I was there to get a simple loan to consolidate some unexpected medical bills. My credit score was great. I always paid my credit card bills on time. In my mind, this was going to be a quick 10-minute meeting ending in a handshake.
The loan officer typed furiously on his keyboard for what felt like an eternity. He finally stopped, pushed his glasses up his nose, and let out a soft sigh.
"Your credit history is excellent," he said, looking at the screen instead of me. "But unfortunately, we cannot approve you today. Your ratio is just too high."
I felt a cold drop in my stomach. What ratio? I had money in the bank. I had a steady job. How could I be rejected for a loan when I was doing everything "right"?
That was the exact moment I learned a very hard financial lesson. The banks do not just look at whether you pay your bills. They look incredibly closely at exactly how much of your paycheck is already promised to someone else before you even wake up in the morning.
This hidden metric completely controls your financial freedom. It dictates whether you can buy a house, get a decent car loan, or even open a new line of credit.
Today, we are going to break down exactly what this metric is, why the banks care so much about it, and exactly how you can fix yours starting this afternoon.
Quick Summary
- Your debt-to-income (DTI) ratio compares your gross monthly income to your total monthly debt payments.
- Lenders use this specific number to measure your borrowing risk and predict if you will default.
- A DTI below 36% is generally considered excellent, while anything above 43% can trigger automatic loan rejections.
- You can improve your ratio by aggressively paying down existing balances or legally increasing your gross taxable income.
Table of Contents
- The Silent Rejection: A Number You Didn't Know Mattered
- What Exactly Is a Debt-to-Income Ratio?
- Real-Life Math: How to Calculate Your Own Number
- Why Lenders Are Terrified of High DTI Ratios
- The Big Confusion: DTI vs. Credit Score
- Front-End vs. Back-End Ratios Explained
- Actionable Steps to Lower Your Ratio Today
Key Takeaways
- Math Matters: You calculate DTI by dividing your total monthly debt by your gross (pre-tax) income.
- Credit Scores Are Not Enough: Excellent credit cannot save you if your income is already stretched too thin.
- The 43% Rule: This is the absolute ceiling for most standard mortgages in the financial world.
- Net vs. Gross: Always use your income before taxes and deductions when doing this math.
What Exactly Is a Debt-to-Income Ratio?
Imagine you have a large bucket of water. Every single month, that bucket gets filled up to the top. This bucket represents your total monthly income.
Now, imagine there are several holes drilled into the bottom of this bucket. One hole is for your rent or mortgage. Another hole is for your student loans. A third hole is for your minimum credit card payments.
Before you even have a chance to take a drink from the bucket, a large portion of the water has already leaked out to pay these fixed obligations.
Your debt-to-income ratio is simply the mathematical measurement of how much water is leaking out compared to how much water went in.
It is a percentage that tells a bank exactly how much of your paycheck is already spoken for. If too much of your money is tied up in existing loans, a lender will not want to give you another one. They know that if one tiny financial emergency happens, your bucket will run completely dry.
Real-Life Math: How to Calculate Your Own Number
Let us look at a completely realistic scenario so you can see exactly how the banks do this math.
Meet David. David works as a marketing manager and earns $5,000 every single month before taxes are taken out. This is his gross monthly income.
David feels pretty good about his finances. However, David has a few regular monthly bills that he cannot avoid. He pays $1,200 for his apartment rent, $400 for his car loan, and $400 in minimum payments across his student loans and credit cards.
If we add up all of David's fixed debt obligations, he spends $2,000 a month just servicing his past and present borrowing.
To find his DTI ratio, the bank will divide his total monthly debt (2,000) by his gross monthly income (5,000). The result is 0.40, or 40%. Here is exactly what David's financial picture looks like on a loan application:
In the eyes of a bank, 40% of David's income vanishes immediately. He only has 60% left over to buy groceries, pay for gas, cover utility bills, and handle emergencies.
Why Lenders Are Terrified of High DTI Ratios
Banks are not emotional institutions. They do not care how nice you are or how hard you work. They only care about statistics and risk management.
Historical data tells lenders a very clear story. People with a high percentage of their income tied to debt are statistically much more likely to miss future payments.
If your ratio is sitting at 50%, it means half of everything you earn goes straight to creditors. If your car breaks down next week, or if you get sick and miss three days of work, your financial system will crash.
Lenders care about your debt-to-income ratio because it acts as a stress test. They want to see if your monthly budget has enough "breathing room" to handle a brand new loan payment without pushing you into bankruptcy.
Pro Tip: When I first calculated my own ratio years ago, I made a massive mistake. I used my net income—the amount that actually hit my checking account after taxes and health insurance. My ratio looked terrifyingly high! Always remember that banks use your gross income (before any taxes are taken out) to calculate this number.
The Big Confusion: DTI vs. Credit Score
One of the biggest misunderstandings in personal finance is thinking that a good credit score guarantees a loan approval.
Your credit score and your debt-to-income ratio measure two completely different behaviors. People confuse them constantly, which leads to shocking rejections at the bank.
Your credit score measures your history of paying things back. Your DTI measures your current capacity to pay things back.
You can have a perfect 800 credit score because you never miss a payment. But if your rent and car loans eat up 60% of your income, no lender will give you a mortgage. You simply do not have the cash flow.
Let us look at the distinct differences between these two financial metrics so you never mix them up again.
The Honest Truth: Having a Low DTI vs. High DTI
If you are wondering what happens when you cross certain thresholds, here is a very clear look at the advantages and disadvantages of where your ratio stands.
Pros of a Low DTI (Under 36%)
- You will easily qualify for the lowest possible interest rates.
- Mortgage lenders will fight to approve your application.
- You have high financial flexibility to survive emergencies.
- You can negotiate much better terms on auto loans.
Cons of a High DTI (Over 45%)
- High probability of automatic application denial.
- If approved, you will be hit with aggressive "junk fees" and high interest rates.
- You may be required to add a co-signer to get basic loans.
- High daily stress due to living paycheck to paycheck.
Front-End vs. Back-End Ratios Explained
When you sit down with a mortgage broker, you might hear them throw around terms like "front-end" and "back-end" ratios.
This sounds incredibly complicated, but it is actually very simple. Lenders just split your debt into two different categories to get a clearer picture of your life.
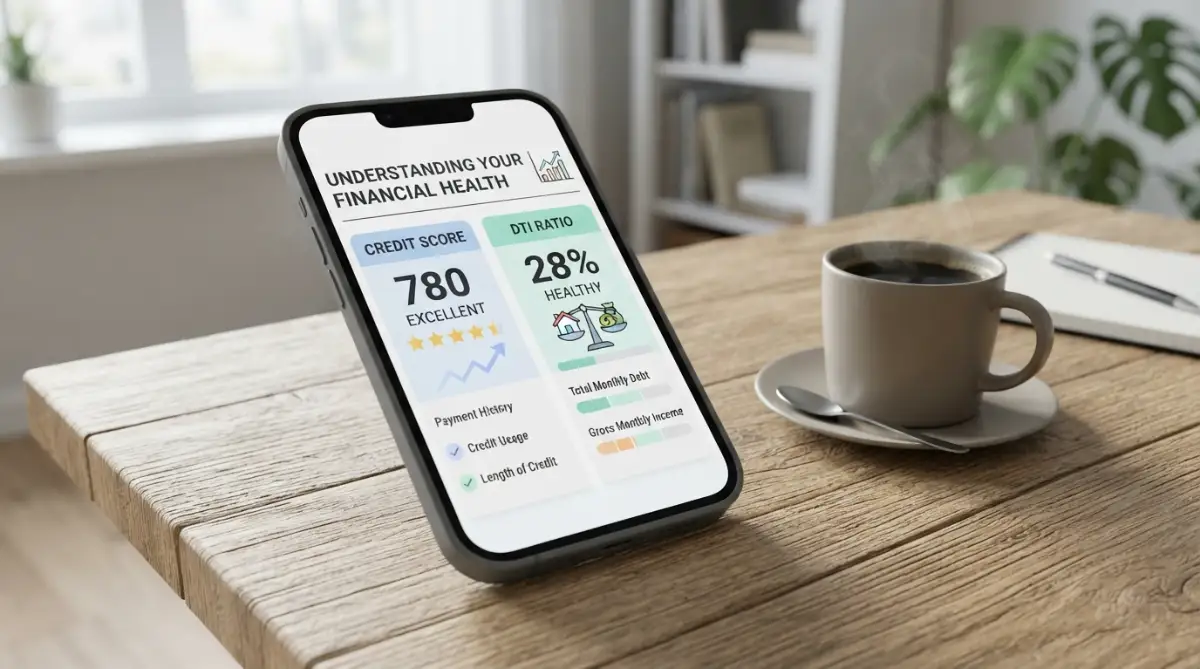
The front-end ratio only looks at your housing expenses. This includes your mortgage payment, property taxes, homeowner's insurance, and HOA fees. Lenders generally want this specific housing number to stay below 28% of your gross income.
The back-end ratio is the big one. This includes your housing expenses plus all of your other minimum monthly debt payments (credit cards, student loans, car notes).
When most lenders talk about your DTI, they are specifically talking about the back-end number. This is the ultimate test of your monthly budget.
Here is how the financial industry generally views your back-end numbers:
Check out this incredibly helpful video explanation to see the math in action:
Understanding exactly how banks view your income can save you thousands of dollars in rejected application fees. Watch this quick breakdown to master the exact formula the banks use before you apply for your next loan.
Actionable Steps to Lower Your Ratio Today
If you just calculated your number and feel sick to your stomach, take a deep breath. This number is not permanent.
Because the formula only uses two variables (debt and income), you only have two ways to fix it. You either need to lower the top number, or raise the bottom number.
Here are the most effective, real-world strategies to fix your ratio quickly.
1. Attack the Smallest Debts First
When the bank calculates your ratio, they do not care about your total overall debt balance. They only care about your minimum monthly payment.
If you have a $500 credit card balance with a $35 monthly minimum, and a $10,000 student loan with a $150 minimum, pay off the credit card completely.
Once that $500 balance hits zero, that $35 monthly obligation vanishes from your credit report. Your total monthly debt obligation immediately drops, instantly improving your ratio.
2. Avoid Opening Any New Accounts
If you are planning to buy a house in the next six months, absolutely freeze your credit activity.
Do not finance a new sofa. Do not take out a new auto loan. Do not open a store credit card to save 10% at the register.
Every single new minimum payment you add to your life increases your total monthly debt. This directly damages your ratio right before the biggest financial transaction of your life.
Expert Tip: Many people completely ruin their mortgage applications by buying a brand new truck the month before they close on a house. The new $600 truck payment pushes their DTI over the maximum limit, and the mortgage is instantly denied.
3. Restructure Your Existing Obligations
If you have high-interest credit cards eating up your monthly cash flow, consider a consolidation loan.
If you are paying $600 a month across five different credit cards, you might be able to consolidate them into one single personal loan with a monthly payment of $350.
By restructuring the debt and extending the term slightly, you just removed $250 from your monthly debt obligations. The bank sees a much healthier cash flow, making you a safer bet.
4. Strategically Increase Your Gross Income
Because your gross income is the denominator in the formula, increasing it lowers your final percentage.
However, banks require a paper trail. You cannot just tell a lender you plan to start mowing lawns for cash.
If you want to use extra income to lower your ratio, it must be documented. Taking on a W-2 part-time job, negotiating a documented salary raise at your current employer, or showing two consistent years of freelance tax returns will force the bank to use a higher income number.
Ultimately, understanding this financial metric puts the power back in your hands. You no longer have to sit in a bank branch hoping for a "yes." By calculating your numbers ahead of time, you will know exactly what the lender sees long before they even print the application.
Strategic Moves to Master Your Monthly Cash Flow
Fixing your borrowing limits is not just a one-time trick. It requires building solid habits that keep your numbers looking beautiful to lenders year after year.
Most people try to rush the process right before they buy a house. Instead, you need to treat your monthly obligations like a garden that needs regular pruning.
When you learn how to create a personal budget when living paycheck to paycheck, you suddenly gain complete visibility over where your