
🕒 Reading Time: 14 Mins | ✍️ Reviewed By: FinanceInfoIn Editorial Team
When the Payment Dates Collide: A Quiet Crisis
A few weeks ago, a reader named Marcus sent an email that practically vibrated with panic.
He was managing five separate loan accounts at the same time: an auto loan, two personal consolidation balances, a private student loan, and a home repair installment plan. Every month, his phone calendar lit up like a Christmas tree with alerts.
The turning point came when his auto lender moved his billing date up by three days due to a bank holiday weekend. That tiny shift caused an automated debit to fire before his paycheck cleared.
The result was an immediate domino collapse. His checking account went negative by $42, triggering an overdraft fee.
Because the account was overdrawn, his next scheduled loan payment bounced, slapping him with a $35 returned payment charge. Within forty-eight hours, Marcus was down nearly $160 in penalty charges alone, and two lenders were already blowing up his phone with automated collection calls.
He wrote to me, "I have enough total income to cover the balances, but the timing is killing me. I feel like I'm balancing ten spinning plates while running on a treadmill."
If you're anything like Marcus, you know that managing multiple debts is rarely just about the total balance. The real fight is surviving the operational drag.
You spend your lunch breaks moving twenty dollars from one savings pocket to another just to keep an account from dipping below zero. You constantly calculate which bill can afford to be three days late without getting reported to the credit bureaus.
That constant mental tension drains your focus at work and ruins your sleep. You end up dreading the fifteenth and thirtieth of every single month.
Here is the thing: trying to manage several loans using pure willpower and memory is a guaranteed recipe for burnout. You need a system that builds firewalls between your loans so one mistake doesn't bring the whole house down.
Let's look at why this happens and how to take control of your debt portfolio today.
Table of Contents
-
When the Payment Dates Collide: A Quiet Crisis
-
The Great Confusion: Consolidation vs. Management Plans
-
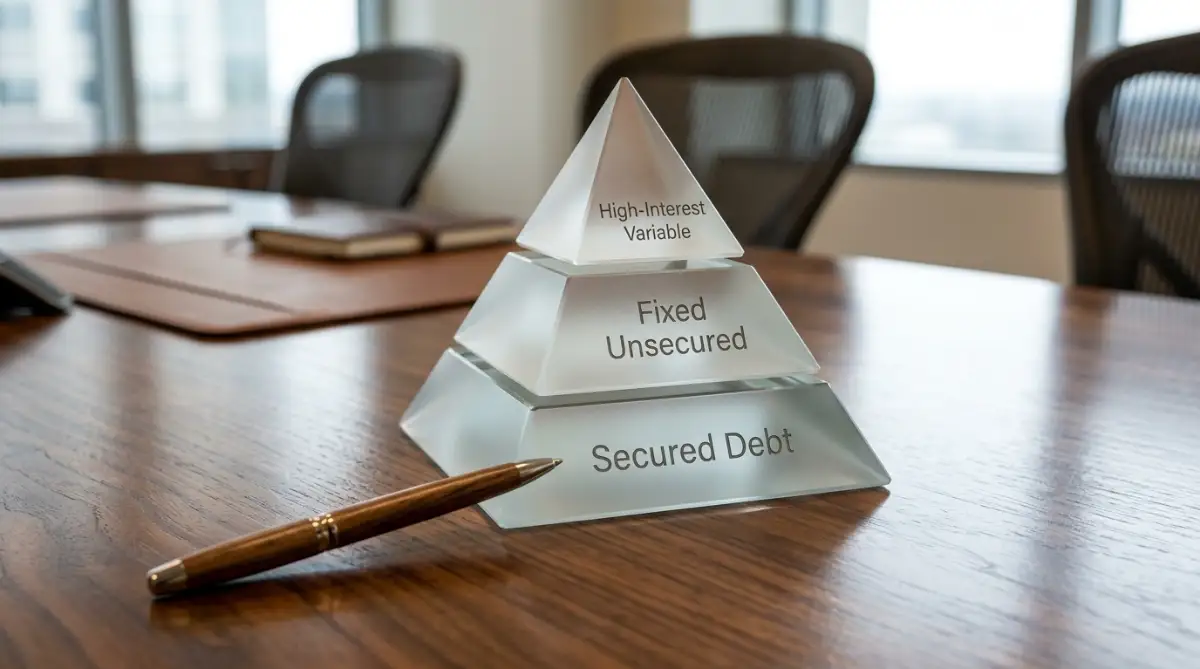
The Anatomy of a Cascading Default
-
Real-Life Numbers: Marcus's Payment Shock
-
Triage Rules: Categorizing Your Loans by Danger Level
-
The Liquidity Dilemma: Aggressive Paydown vs. Cash Cushion
-
Step 1: Unifying Your Billing Calendar
-
Step 2: Neutralizing Cross-Collateralization Clauses
The Great Confusion: Consolidation vs. Management Plans
When people find themselves drowning under several monthly obligations, they usually look for a quick exit. That is where most borrowers run headfirst into a massive trap.
A lot of people assume that a Debt Consolidation Loan and a Debt Management Plan (DMP) are just two different names for the same service. That assumption can cost you thousands of dollars and trash your credit rating.
To put it simply, choosing the wrong option can strip away your financial flexibility right when you need it most.
Let's look at how these two common alternatives actually stack up against each other.
If you still possess a decent credit score, taking out a consolidation loan can buy you breathing room. But if your cash flow is already in the red, a structured management program offered by a non-profit agency is often the far safer route.
The Anatomy of a Cascading Default
In personal finance, risk does not move in a straight line. It compounds.
When you owe money to four or five lenders, they are all competing for the exact same pool of cash sitting in your checking account. The lender that pulls first gets paid; the lender that pulls fifth gets an overdraft notice.