
🕒 Reading Time: 13 Mins | ✍️ Reviewed By: FinanceInfoIn Editorial Team
Quick Summary
Medical billing can easily overwhelm anyone trying to manage their budget. A copay is a simple, fixed dollar amount you pay upfront for a specific health service. Coinsurance is a percentage of the total medical bill that you share with your insurance provider. You usually start paying this percentage only after you have fully paid your yearly deductible.
The Unexpected Shock at the Pharmacy Counter
I clearly remember standing at the local pharmacy counter feeling completely defeated. I had a terrible sinus infection, a splitting headache, and barely any energy left in my body. I handed over my brand new health insurance card, expecting to pay a simple 15 dollar fee for my generic antibiotics.
Instead, the pharmacist looked at the screen and calmly asked for 145 dollars. My heart instantly sank to my stomach. I only had about 40 dollars left in my bank account until payday. I stared at the pharmacist in total disbelief, asking how a simple prescription could cost so much with so-called "premium" insurance coverage.
She kindly explained that my plan did not have a flat fee for this specific tier of medication. Instead, I was responsible for a percentage of the total drug cost because I had not met my deductible yet. I had to walk away empty-handed that day, feeling embarrassed and physically miserable.
That specific moment taught me a very harsh reality about adulting. Having an active health plan does not automatically mean your medical care is fully paid for. If you do not understand the exact terms hidden in your paperwork, you will face unexpected financial burdens.
Millions of families deal with this exact same stress every single day. We skip necessary doctor visits simply because we are terrified of the unknown final bill. The constant worry about hidden medical costs destroys our mental peace and drains our hard-earned savings.
By the time you finish reading this guide, you will never feel that level of confusion again. I am going to explain exactly how your healthcare coverage works using everyday examples. You will finally gain the confidence to walk into any clinic knowing exactly what you owe.
Breaking Down the Fixed Fee Concept
Let us start by talking about the easiest term to understand in your entire policy. A copay is simply a flat, fixed rate you pay for a specific healthcare service. Think of it like paying a cover charge to get inside a nightclub or an amusement park.
You pay your set entry fee, and the insurance company handles the rest of the standard cost. If your policy says your primary care visit is 20 dollars, that is exactly what you hand to the receptionist. It does not matter if the doctor spends ten minutes or an hour talking to you.
The flat fee remains completely unchanged regardless of the total bill for that specific standard service. This makes budgeting for routine healthcare incredibly predictable and stress-free for your family.
Notice how simple those numbers are? You do not need a calculator to figure out your responsibility. However, you must remember that different services always have different flat rates attached to them. Visiting a heart specialist will always cost more upfront than visiting your family doctor for a cold.
The Percentage Split: Sharing the Burden
Now we arrive at the concept that causes the most financial anxiety for patients. Coinsurance is not a flat rate, but rather a percentage of the total medical bill. You and your health plan agree to split the final cost of your treatment.
A very common split is the 80/20 rule found in many standard employer plans. This means the insurance provider pays 80 percent of the final approved medical bill. You are then legally responsible for paying the remaining 20 percent out of your own pocket.
Imagine you go out to dinner with a wealthy friend who agrees to pay most of the check. If the total dinner bill is 100 dollars, your friend pays 80 dollars and you pay 20. But if you order a massive feast that costs 10,000 dollars, your 20 percent share suddenly becomes 2,000 dollars.
A Quick Intro to Medical Math
Watch this quick visual breakdown to understand exactly how medical percentages are calculated in real-time. This simple video explains the math behind hospital bills much better than reading a complex policy document.
Expert Tip: I used to completely ignore the "allowed amount" section on my medical bills. Always check to ensure your percentage is based on your network's negotiated rate, not the hospital's inflated retail price. If you blindly pay the percentage of the retail price, you are simply throwing your money away.
The Deductible Barrier Before the Split
You cannot fully grasp how the percentage split works without understanding your deductible. Your deductible is the initial amount of money you must pay yourself before your health provider starts sharing the major costs. It acts as a financial barrier you have to break through.
Let us say your plan has a 1,000 dollar deductible. If you need a surgery that costs 5,000 dollars, your percentage split does not start immediately. You must first pay that initial 1,000 dollars completely on your own.
Once that barrier is cleared, the remaining 4,000 dollars of the surgery bill is subject to the percentage split. If you have an 80/20 plan, you will owe 20 percent of that remaining 4,000 dollars, which is 800 dollars. So, your total out-of-pocket cost for the surgery would be 1,800 dollars.
This is exactly why high-deductible plans feel so punishing when you experience a sudden medical emergency. You are hit with the full, unassisted cost of treatment until that high threshold is finally crossed.
Real-Life Scenarios: How They Actually Work
Let us look at a practical scenario to see how these two systems work together in real life. Imagine you wake up in the middle of the night with severe abdominal pain. You decide to visit the emergency room, terrified that your appendix is bursting.
At the ER front desk, the receptionist asks you for a 150 dollar emergency room copay. You hand over your debit card, assuming this flat fee covers your entire nighttime visit. The doctors run a CT scan, draw blood, and eventually determine it is just a bad stomach virus.
A month later, you receive a massive bill in the mail for 3,000 dollars. You stare at the paper, wondering why you are being billed when you already paid the entry fee. The flat fee only covered the basic facility charge of using the emergency room itself.
The expensive CT scan and the laboratory blood work fall under a completely different category. Those specific diagnostic services are subject to your deductible and your coinsurance percentage. Because you had not met your yearly deductible, you are now entirely responsible for that heavy diagnostic bill.
The Ultimate Safety Net: Out-of-Pocket Maximum
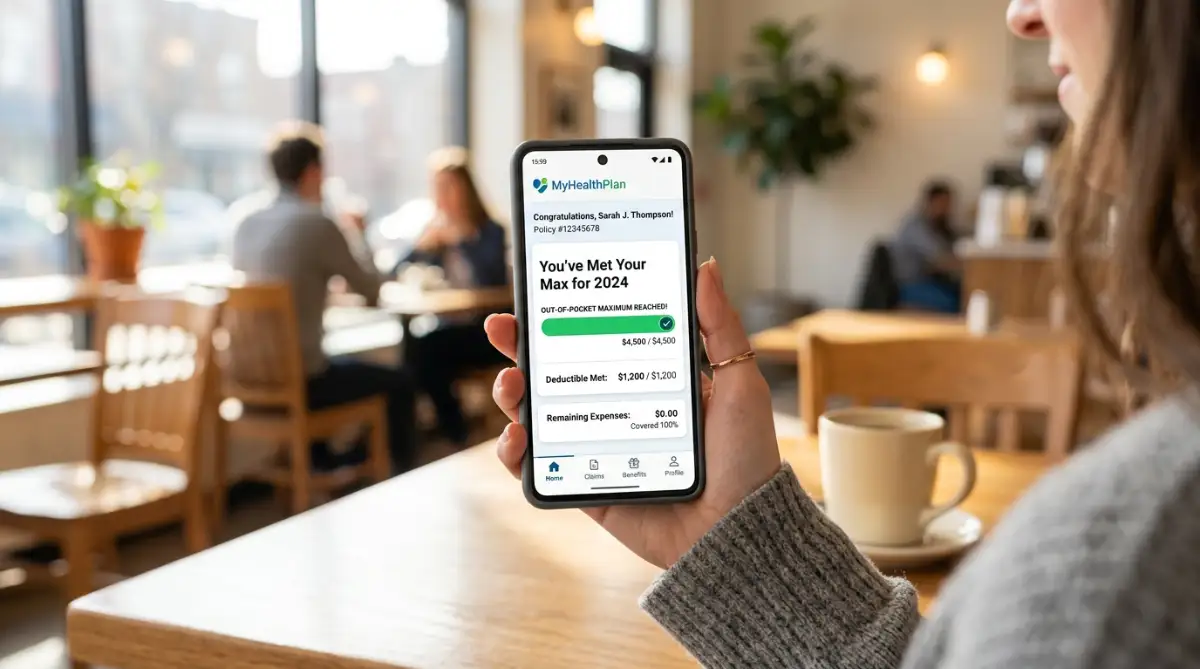
If the idea of paying endless percentages scares you, there is a very important safety net built into your policy. It is called the out-of-pocket maximum, and it is the financial ceiling of your healthcare plan. This is the absolute most you will ever have to pay from your own bank account during a single policy term.
Think of it as a financial stop-loss switch. Let us imagine your out-of-pocket maximum is set at 5,000 dollars. Throughout the year, every flat fee, deductible payment, and percentage split you pay gets added to a running tally.
If you get into a severe accident and require multiple expensive surgeries, your 20 percent share could technically reach 10,000 dollars. However, because your safety ceiling is 5,000 dollars, your billing stops the moment you hit that exact number. After that threshold, your provider pays 100 percent of your approved medical bills for the rest of the term.
Knowing this maximum number is incredibly empowering. It gives you a clear worst-case scenario to prepare for financially. You can safely build an emergency savings fund matching that exact ceiling amount.
Choosing the Right Plan for Your Family
When open enrollment comes around, you will see dozens of plans offering different payment structures. How do you choose the right balance between flat fees and percentage splits? The answer entirely depends on your expected medical needs and your current financial stability.
If you have young children who catch every bug at school, you will be at the doctor constantly. In this case, you want a plan with low, predictable flat fees for office visits. You will happily pay a slightly higher monthly premium just to know that every pediatric visit only costs 20 dollars.
On the other hand, maybe you are a healthy, single person who visits the doctor once a year. You might prefer a plan with a higher deductible and a higher percentage split. Your monthly premium will be much cheaper, and you only risk paying high costs if a rare emergency happens.
Just remember to always read the Summary of Benefits document before signing anything. Look closely at the pharmacy tier list to see exactly how your specific medications are classified. A drug that requires a flat fee on one plan might require a hefty percentage split on another.
Taking control of your healthcare costs starts with understanding these basic terms. You now know the difference between paying a simple entry fee and sharing a massive hospital bill. Next time you stand at a pharmacy or clinic counter, you will know exactly how to read your bill.
Advanced Secrets for Managing Your Healthcare Budget
Let us talk about taking real control of your upcoming hospital visits. You already know the basic definitions, but knowing the rules is only half the battle. Now, we need to look at how you can actively protect your hard-earned savings.
One of the smartest things you can do is aggressively verify network status before scheduling any procedure. Many patients assume that if a hospital accepts their card, every doctor inside that building does too. This is a very dangerous and expensive assumption that catches families off guard every single day.
Imagine walking into an all-you-can-eat buffet, but later finding out the dessert station belonged to a completely different restaurant. You would be furious when they handed you a separate, massive dessert bill. That is exactly what happens when an out-of-network anesthesiologist works on your surgery without your knowledge.
To fully protect yourself, you should always master choosing the right health coverage for your family. You must proactively call your insurance company or network provider directly to confirm they are in-networky for your specific network tier. Do not just ask if they "accept" your insurance, because accepting it simply means they will bill it for you.
Accepting your card does not mean they have a specially contracted discount rate. You can easily avoid these hidden charges by asking a few simple questions upfront. Research from trusted organizations like the Kaiser Family Foundation shows that surprise medical bills are a leading cause of financial stress for families.
Pro Tip: I always ask the receptionist to write down the exact billing code for my upcoming test. I then call my insurance company directly with that specific code to verify exactly what my percentage split will be before I ever sit in the waiting room.
Quick Action Checklist
- Call your insurance hotline and ask if your specific clinic location is completely in-network.
- Ask the clinic if the lab processing your bloodwork is also inside your approved network.
- Request the specific medical billing codes for any upcoming major procedures.
- Match those exact codes with your Summary of Benefits document to see your expected cost.
- Keep a dedicated folder for all your medical receipts to track your progress toward your safety ceiling.
Taking these tiny proactive steps will save you thousands of dollars over your lifetime. You will never again have to blindly hand over your credit card hoping for the best.
The Most Expensive Billing Traps You Must Avoid
The healthcare system is incredibly complex, and innocent mistakes can cost you dearly. One of the biggest errors patients make is completely ignoring their Explanation of Benefits (EOB). Your EOB is a letter from your provider explaining exactly what they paid and what you owe.
Many people throw this document in the trash, assuming it is just a standard bill or junk mail. Your EOB is actually your ultimate cheat sheet for catching illegal billing errors. If your clinic sends you a bill for 500 dollars, but your EOB says you only owe a 40 dollar flat fee, the clinic made a mistake.
If you do not completely understand how your deductible works, you will blindly pay that inflated 500 dollar invoice. I once almost paid a massive hospital charge because I was too scared to question the authority of the billing department. I finally checked my EOB and realized my provider had already covered 80 percent of that exact charge.
Another massive mistake is staying perfectly quiet when a medical claim is randomly rejected. Over 60 percent of denied healthcare claims are never appealed by the patient. People simply accept the massive rejection letter and drain their savings to pay the retail price.
Just like you would fight to prevent claims from being unfairly denied on your car, you must aggressively appeal medical rejections. Often, a claim is denied simply because the doctor's office misspelled your name or entered the wrong diagnostic code. A simple five-minute phone call to the billing department can legally force them to reprocess and approve your claim.
You should also be heavily involved in reading your insurance declaration page every single year. Health plans constantly change their flat fee structures and percentage splits behind the scenes. A medication that required a simple 10 dollar fee last year might suddenly require a 30 percent split this year.
Your Blueprint for Stress-Free Medical Visits
You now have the exact tools needed to navigate the confusing world of medical billing. You understand that a copayment is simply your predictable entry fee for basic services. You also know that coinsurance is the percentage you share with your provider for major medical procedures.
By closely monitoring your deductible, you know exactly when your provider will start helping with the heavy costs. You can also rest easy knowing your out-of-pocket maximum is there to protect you from total financial ruin. Medical emergencies are scary enough on their own without the added terror of unpredictable invoices.
I personally review every single medical receipt now with complete confidence and zero anxiety. It feels amazing to walk into a clinic and know exactly what my financial responsibility will be before I even sit down. You can easily achieve this same level of peace by taking just five minutes to read your policy documents today.
Which medical bill are you planning to review first? Let me know in the comments below!
Key Takeaways
- Predictability: Copayments offer predictable, flat-rate costs for routine visits and basic medications.
- Proportional Costs: Coinsurance makes you responsible for a specific percentage of a larger medical bill.
- The Deductible Rule: You normally have to pay your full deductible out of your own pocket before your percentage-based coverage kicks in.
- Maximum Protection: The out-of-pocket maximum is the absolute highest amount you will ever pay in a single policy period.
Smart Answers to Your Medical Billing Worries
Can I negotiate my coinsurance percentage?
No, your percentage split is a strict contract agreement between you and your provider. However, you can certainly negotiate the total retail price directly with the hospital billing department before your percentage is applied.
Does a copayment count toward my deductible?
In most standard plans, flat fees do not count toward your initial deductible barrier. However, they almost always count toward your total out-of-pocket maximum for the year.
What happens if I pay a flat fee but the doctor is out-of-network?
If the doctor is out-of-network, your provider will likely reject the claim entirely. The clinic will then send you a massive bill for the full retail price of the visit, regardless of the small fee you paid upfront.
Do prescription costs count toward the out-of-pocket maximum?
Yes, any money you spend on covered generic or brand-name prescriptions will help you reach your safety ceiling. Just ensure you are using a pharmacy that is approved within your specific network.
Why did I receive a bill after paying my entry fee at the clinic?
Your flat fee usually only covers the doctor's physical time and the room usage. If the doctor orders extra lab work, x-rays, or special tests, those are billed separately and usually require a percentage split.
Is it better to have a high flat fee or a high deductible?
This depends entirely on how often you visit the hospital. Frequent visitors benefit greatly from predictable flat fees, while healthy individuals often prefer higher deductibles to secure a cheaper monthly premium.
Will my emergency room entry fee be waived if I am admitted?
Yes, most health plans will completely waive your emergency room flat fee if you are officially admitted into the hospital for an overnight stay. You will then transition directly into your deductible and percentage split phase.
How do I know if my procedure requires a percentage split?
You should immediately review your Summary of Benefits document provided by your insurance company. You can also call the member services number on the back of your card to ask about your specific procedure code.
Can a hospital change my out-of-pocket maximum mid-policy?
No, your financial safety ceiling is legally locked in for the entire duration of your annual policy term. It will only reset or change when you renew your contract during the next open enrollment period.
What should I do if my insurance denies a covered service?
You should immediately call your provider and ask for the exact reason for the denial. If it is a simple coding error, the doctor's office can easily fix it and resubmit the claim for full approval.