
🕒 Reading Time: 13 Mins | ✍️ Reviewed By: FinanceInfoIn Editorial Team
Opening my thirteenth auto loan statement over a lukewarm cup of coffee at my kitchen table nearly made me sick to my stomach. I had dutifully sent the bank $400 every single month without missing a beat, meaning $4,800 had left my checking account. Yet, looking at the bottom of that crisp paper statement, my actual loan balance had only dropped by a measly $1,900. I sat there staring at the numbers with a knot in my chest, wondering if the bank had made a massive clerical error or if I was being robbed in broad daylight.
It felt like running on a treadmill at full speed while going absolutely nowhere. Calling customer service didn't help much either, because the rep just threw around robotic banking terms that made my head spin even faster. It took me a full weekend sitting with a calculator to figure out what was actually happening behind the scenes.
Why Your Loan Balance Barely Moves at First
If you're anything like me, seeing your hard-earned cash vanish into a financial black hole is deeply exhausting. You work overtime, skip dining out, and make your monthly payments on time, expecting to see your debt shrink at a steady pace. Instead, the balance crawls down at a snail's pace, leaving you feeling trapped in a never-ending cycle of bills.
The reality is that most lenders do a terrible job of explaining how your payments actually get divided. You sign a mountain of paperwork at the closing table, nod politely at a giant spreadsheet of numbers, and just focus on whether you can afford the monthly bill. Nobody stops to tell you that the math is heavily stacked in the bank's favor from day one.
This isn't a glitch, it's actually by design. Banks structure installment loans using a specific mathematical formula so they get their profit upfront before you ever make a real dent in your debt. Once you see how this invisible system operates, you can stop feeling cheated and start taking control of your paycheck again.
You don't need a finance degree to figure this out. To put it simply, we are going to strip away the stiff banking vocabulary and look at what is really happening to your money every month.
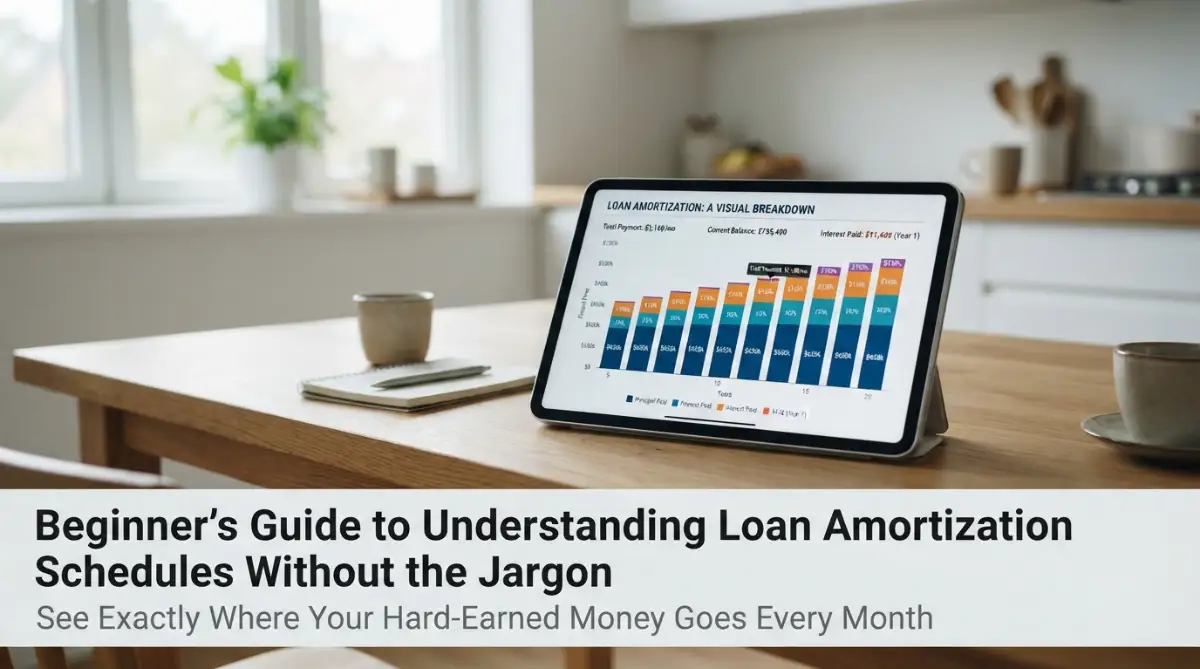
Table of Contents
-
Why Your Loan Balance Barely Moves at First
-
What Is a Loan Amortization Schedule in Plain English?
-
The Seesaw Effect: How Principal and Interest Actually Split
-
Real-Life Math: Inside Sarah’s $20,000 Auto Loan
-
Amortized Loans vs. Revolving Credit: Don't Mix Them Up
-
The Honest Pros and Cons of Amortized Loans
-
How to Read Your Amortization Table Without a Headache
-
Smart Ways to Beat the Bank's Math and Pay Off Debt Early
-
The Hidden Traps That Keep You in Debt Longer
-
Busting the Biggest Amortization Myths
-
Next-Level Hacks to Outsmart Your Amortization Schedule
-
Your Step-by-Step Blueprint to Attack Your Principal Today
-
Your Next Steps to Financial Freedom
-
The Most Common Questions About Loan Schedules (FAQs)
What Is a Loan Amortization Schedule in Plain English?
Let's strip away the fancy Latin roots right now. In the banking world, "amortization" simply means killing off a debt slowly over time through regular, fixed payments. An amortization schedule is just a complete table showing every single payment you'll make from the day you borrow the money until the day you owe zero dollars.
A lot of people assume that if you have a fixed monthly payment of $500, the bank takes the exact same fee out of every check. That's not how it works at all. While the total dollar amount leaving your bank account stays identical each month, the way the bank slices up that payment changes every thirty days.
Every monthly payment you send in gets split into two buckets:
-
Principal: This is the actual chunk of money you borrowed and still owe back.
-
Interest: This is the rental fee the bank charges you for the privilege of using their money.
Here is the thing: at the start of your loan, the interest bucket is huge and the principal bucket is tiny. As the months roll by and your balance slowly drops, those buckets gradually swap sizes.
The Seesaw Effect: How Principal and Interest Actually Split
Think of your loan like a playground seesaw. When you make your very first payment, the "Interest" side of the seesaw is sitting heavy on the ground, while the "Principal" side is way up in the air. Most of your money goes straight into the bank's pocket as profit, and only a sliver goes toward lowering your debt.
Let's look at why this happens. Interest isn't pulled out of thin air; it's calculated each month based on how much total money you currently owe right then. Since your loan balance is at its absolute highest on month one, the interest charge for month one is also at its absolute highest.
Once that first tiny sliver of principal gets paid off, your total loan balance shrinks by a few bucks. Next month, when the bank calculates your interest fee on that slightly smaller balance, the fee goes down by a few cents. Because your total monthly payment is locked in at a fixed rate, those extra few cents automatically shift over to pay down more principal.
Want to see this seesaw effect in action before we look at the numbers? Watch this quick, visual breakdown to see how your monthly payments shift over time, then keep reading below to learn the exact trick to flip the math in your favor.
Real-Life Math: Inside Sarah’s $20,000 Auto Loan
Looking at abstract rules is boring, so let's use real numbers to see how this plays out in everyday life. Meet Sarah, who takes out a
Here is the breakdown of how the bank calculates her very first bill. First, they divide her 6% annual interest rate by 12 months, which equals